
2026-05-08 · personal, home, claims
Updated: 2026-08-13
By InsuraFAQ Editorial Team · Reviewed for accuracy
How to File a Home Insurance Claim: Complete Guide
Key Takeaways
- Document all damage with photos and video before cleaning up or making permanent repairs.
- Contact your insurer as soon as possible; most policies require prompt notification.
- Understand your deductible and whether your policy pays replacement cost or actual cash value before accepting a settlement.
- Keep receipts for temporary repairs and additional living expenses, as these may be reimbursable.
- Small claims near or below your deductible may not be worth filing due to potential premium increases.
Introduction
When your home is damaged by a storm, fire, burst pipe, or break-in, knowing how to file a home insurance claim can make the difference between a smooth recovery and a frustrating ordeal. The process involves several steps, from documenting the damage to negotiating a fair settlement. This guide walks you through every stage so you know what to expect and how to protect your interests. For a quick-reference checklist, see the home claims step-by-step guide.
How to file a home insurance claim, step by step
To file a home insurance claim, document the damage with photos and video, review your policy and deductible, then contact your insurer to open a claim. An adjuster assesses the damage. Get independent contractor estimates, discuss any disagreement with the insurer, and ask what receipts are needed for any further payment. Payment depends on your policy, limits, deductible, and the covered loss.
-
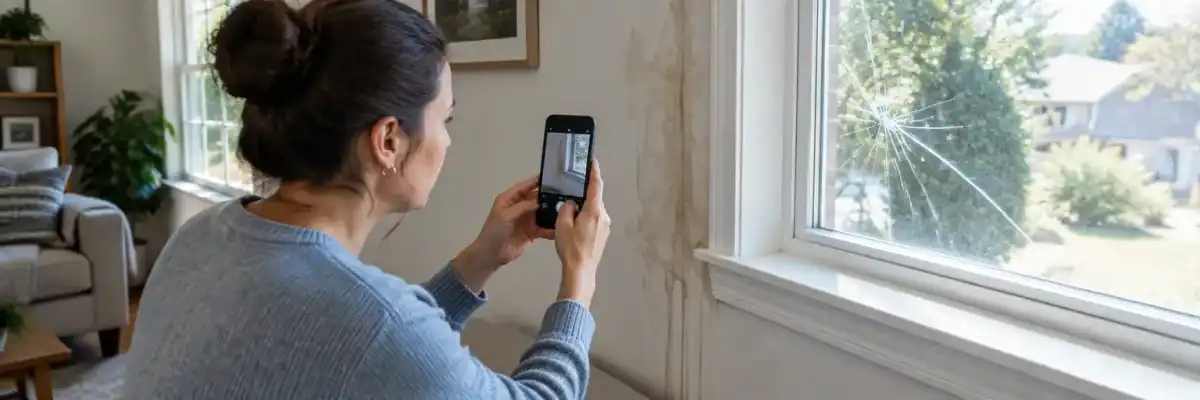
Document the damage.
Take wide-angle and close-up photos and video of every damaged area and item before you clean up or make permanent repairs.
-
Review your policy and deductible.
Pull your declarations page so you know your dwelling, personal property, and loss-of-use limits, plus the deductible that applies to this peril.
-
Contact your insurance company.
Call the claims line, use the mobile app, or file online with your policy number, date of loss, and a short description of what happened.
-
Meet with the adjuster.
Walk the adjuster through every affected area and request a written, line-item scope of loss before they leave.
-
Get independent repair estimates.
Collect at least two estimates from licensed contractors so you can compare them against the adjuster’s figure.
-
Negotiate the settlement.
Review the offer line by line. If your contractor estimates are higher, submit them as a supplement and request a re-inspection.
-
Complete repairs and submit receipts.
Ask your insurer what documentation is needed for any remaining replacement-cost payment; policy terms and limits apply.
Before You File: Immediate Steps
Before you contact your insurance company, take these steps to protect yourself and preserve evidence.
Document the damage
Take detailed photos and video of all affected areas and damaged belongings. Capture wide shots that show the full scope of damage and close-ups of specific items. If possible, include timestamps. This documentation is critical evidence for your claim.
Prevent further damage
Most homeowners policies require you to take reasonable steps to prevent additional damage. Cover broken windows with tarps or plywood, shut off water if a pipe burst, and move undamaged belongings away from affected areas. Save all receipts for materials and emergency repairs, as your policy typically reimburses these costs.
Do not throw away damaged items
Keep damaged items until the adjuster has inspected them. If you must remove debris for safety, photograph everything thoroughly first. Discarding items before inspection can complicate your claim.
Contact emergency services if needed
If there is a fire, structural collapse, or any threat to safety, call 911 first. Your safety is always the top priority. File a police report for theft or vandalism, as your insurer will likely require it. Learn more about theft claims specifically.
How to File Your Claim
Contact your insurer
Most insurance companies offer multiple ways to start a claim: phone, mobile app, or online portal. Check your policy documents or your insurer’s website for the claims phone number. Many insurers have 24/7 claims hotlines for emergencies.
When you call, have the following ready:
- Your policy number
- Date and time the damage occurred
- A description of what happened
- Photos and video of the damage
- A police report number (if applicable)
- A list of damaged or stolen items with approximate values
Filing deadlines
Most policies require you to report damage “promptly” or “as soon as practicable.” Some states set specific filing deadlines. Waiting too long can give your insurer grounds to reduce or deny your claim. File as soon as you have documented the damage, even if you are still assessing the full extent.
The Claims Process: What Happens Next
Claim number assigned
After you report the damage, your insurer assigns a claim number. Keep this number handy for all future communication about your claim.
Adjuster visit and inspection
Your insurer assigns a claims adjuster to assess the damage, often through an inspection. The adjuster estimates repair costs. You do not have to accept the adjuster’s first estimate. Be present during an inspection if possible, and point out all damage you have documented.
Getting repair estimates
Get at least two independent repair estimates from licensed contractors in addition to the adjuster’s estimate. If your estimates differ significantly from the adjuster’s, share them with your insurer. Having multiple estimates strengthens your position during negotiations.
Settlement offer
Based on the adjuster’s report, your insurer makes a settlement offer. Review the offer carefully. If it seems too low, you can negotiate, provide additional documentation, or request a re-inspection. You are not required to accept the first offer.
How Long Does a Home Insurance Claim Take?
Claim timelines vary with the damage, policy, insurer, and applicable state rules. Ask your insurer for an estimate and any deadlines that apply, and keep a record of communications. The NAIC’s settlement guide explains that payment may involve separate stages for different parts of a claim. Contact your state insurance department for rules applicable to your situation.
Understanding Your Payout
Replacement cost vs. actual cash value
Your payout depends on whether your policy uses replacement cost or actual cash value, as well as its terms, limits and deductible. Replacement cost reflects repair or replacement using similar materials; actual cash value takes age and wear into account.
How deductibles work
Your deductible is the amount you pay out of pocket before your insurer covers the rest. For example, if you have a $1,000 deductible and $8,000 in covered damage, your insurer pays $7,000. Some policies have separate, higher deductibles for specific perils like wind or hail.
Depreciation and holdback
With replacement cost policies, your insurer may initially pay actual cash value and hold back the difference. Ask what repairs and documentation are required for any additional payment, and check your policy’s limits and deadlines.
When should I NOT file a home insurance claim?
Not every loss is worth filing on. In several common scenarios, paying out of pocket is the smarter move:
- The damage is below or near your deductible. If your deductible is $1,500 and the repair runs $1,700, you walk away with $200 and a claim on your record. Get a contractor estimate first.
- You already have two claims in the past three years. Your claim history may affect renewal or premiums, depending on the insurer and state rules. Ask your insurer or agent about your circumstances.
- The damage may be wear and tear. Home insurance is not a maintenance contract. Review your policy and ask the insurer whether the specific damage and cause are covered.
- The cause may be excluded. Flood and earthquake are generally excluded from standard homeowners policies, and water damage coverage depends on the cause and policy. Review the policy and ask your insurer before deciding.
- The premium impact will exceed the payout. A claim can affect your premium, depending on your insurer and applicable rules. For a $1,000 net payout, a $200/year surcharge over five years is a net loss. For the monthly and annual homeowners premium baseline the surcharge sits on top of, see our homeowners insurance cost guide.
As a general rule, reserve claims for sudden damage that clearly exceeds your deductible by a meaningful margin. For more on managing your costs, see how much home insurance do I need.
Common Claim Scenarios
Different types of damage involve different coverage rules and processes:
- Water damage. Coverage depends on the source of water and policy exclusions; wear and tear and maintenance are generally not covered. See the guide on water leak claims and the home warranty vs. home insurance guide for how those products differ.
- Wind and storm damage. Most homeowners policies cover wind, hail, and storm damage to the structure and contents. Flood damage requires separate flood insurance. Read more about wind damage claims.
- Theft and burglary. Standard homeowners policies cover stolen belongings and damage caused during a break-in, subject to sub-limits for certain categories like jewelry. Learn about the theft claim process.
- Manufactured or mobile home claims. Factory-built housing is covered under an HO-7 or a dedicated mobile-home policy form rather than a standard HO-3, so dwelling valuation, ACV-versus-replacement-cost defaults, and eligible perils can differ from a site-built home claim. Read the coverage-form specifics in our mobile home insurance guide before filing.
If Your Claim Is Denied
A denial does not have to be the final answer. Common reasons insurers deny claims include:
- The damage is from an excluded peril (such as flooding or earth movement)
- The insurer determines the damage was caused by lack of maintenance
- The claim was filed after the policy’s reporting deadline
- The damage amount is below the deductible
If you believe the denial is wrong, you have options. Review the denial letter carefully, gather additional evidence, and file a formal appeal with your insurer. You can also hire a public adjuster or consult your state’s department of insurance. For a complete walkthrough, see the claims denial and appeals guide.
Frequently asked questions
How do I file a home insurance claim?
To file a home insurance claim, document the damage with photos and video, review your policy and deductible, then contact your insurer by phone, app, or online portal. Provide your policy number, date of loss, and a description of what happened. Your insurer assigns a claim number, sends an adjuster to inspect the damage, and issues a settlement offer based on the adjuster’s report. Keep all receipts and written communication throughout the process.
How long do I have to file a home insurance claim?
Most home insurance policies require you to notify your insurer “promptly” or “as soon as practicable”. Reporting and proof-of-loss deadlines vary by policy and state. Check the “Duties After Loss” section of your policy for the exact window, and report the damage as soon as you have documented it, even if you are still assessing the full scope.
How long does a home insurance claim take?
The timing depends on the loss, insurer, policy, and applicable state rules. Ask your insurer about the next steps and contact your state insurance department for applicable deadlines.
Will filing a claim raise my premium?
It can. Many insurers increase premiums after a claim, especially if you have filed multiple claims in a short period. The increase depends on the type and size of the claim, your claims history, and your insurer’s policies. One small claim may have little impact, while multiple claims could affect your rate or lead to non-renewal.
What happens if my claim is denied?
A denial is rarely the final answer. Read the denial letter carefully to identify the specific policy provision the insurer cited, then gather supporting evidence — repair estimates, expert opinions, weather reports, or proof of ownership — that addresses the cited reason. Submit a written appeal inside the deadline listed on the letter. If the internal appeal fails, you can file a complaint with your state department of insurance, hire a public adjuster, or consult an attorney. See the full claims denial and appeals guide for the appeal letter structure and escalation paths.
Should I file a home insurance claim for minor damage?
Often no. If the repair cost is close to or below your deductible, you will receive little or no payout, and a claim on your record may affect your premium or renewal, depending on your insurer and state rules. As a rule, reserve claims for damage that clearly exceeds your deductible by a meaningful margin. For minor damage, get a contractor estimate first and compare the out-of-pocket cost to the likely premium impact before deciding.
Can I choose my own contractor for repairs?
Your insurer may recommend contractors. Ask about your choices and check applicable state rules and policy terms. Independent estimates can help you compare costs; check contractors’ licensing and insurance.
What if I disagree with the adjuster’s estimate?
You can get your own repair estimates from licensed contractors and present them to your insurer as a supplement. If you cannot reach an agreement, your policy may include an appraisal process; check its terms. You can also file a complaint with your state’s department of insurance.
Does home insurance cover temporary living expenses?
Most homeowners policies include “loss of use” or “additional living expenses” (ALE) coverage. If your home is uninhabitable due to a covered loss, this pays for hotel stays, restaurant meals, and other reasonable expenses above your normal costs, up to your policy’s limit.
Conclusion
Filing a home insurance claim does not have to be overwhelming if you follow a clear process. Document everything immediately, report the damage promptly, and stay organized throughout the adjuster’s inspection and settlement negotiation. Understand your policy’s terms, especially your deductible and whether you have replacement cost or actual cash value coverage. For detailed guidance on specific situations, explore the claim scenario guides linked throughout this article, or visit the homeowners insurance overview for broader coverage information. The best-handled claim starts before disaster strikes — reviewing your coverage ahead of severe weather with our spring home insurance checklist can close gaps before you ever need to file.
Sources
- National Association of Insurance Commissioners, “What You Need to Know When Filing a Homeowners Claim”
- National Association of Insurance Commissioners, “What You Should Know About Settling a Homeowners Insurance Claim”
- National Association of Insurance Commissioners, “A Consumer’s Guide to Home Insurance”