
2026-04-21 · auto, coverage, comparison
Updated: 2026-11-02
By InsuraFAQ Editorial Team · Reviewed for accuracy
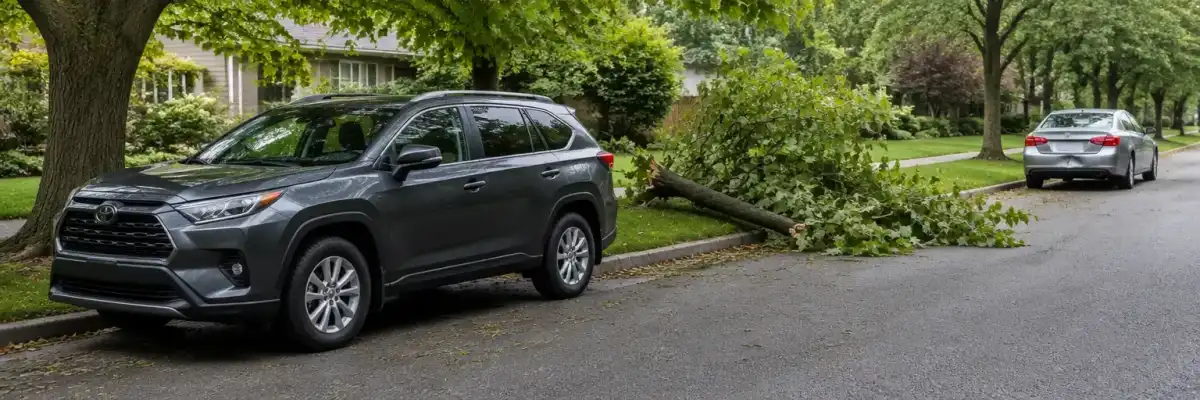
Comprehensive vs. Collision Insurance
At a glance
- Collision: pays for damage when your car hits another vehicle or object — regardless of fault.
- Comprehensive: pays for non-crash events like theft, vandalism, hail, flood, fire, animal strikes, and falling objects.
- Deductibles: Both coverages generally have deductibles; amounts and claim handling depend on the policy.
- Cost: Compare the separate premiums and deductibles in your quotes.
- When required: A lender or lessor may require both on a financed or leased vehicle.
Key Takeaways
- Collision insurance pays to repair or replace your car after a crash, regardless of who is at fault.
- Comprehensive insurance covers non-crash events like theft, hail, flooding, vandalism, and animal strikes.
- A lender or lessor may require both coverages on financed or leased vehicles.
- Each coverage generally has its own deductible; the policy determines how deductibles apply.
- Premiums vary by insurer, vehicle, location and coverage choices.
Introduction
If you have ever shopped for car insurance beyond the state minimum, you have probably seen collision and comprehensive listed as optional coverages. Together with liability, these two coverages make up what most people call full coverage auto insurance. While they are often bundled together, collision and comprehensive protect you in very different situations.
Understanding what each one covers, and when you actually need them, can help you avoid paying for protection you do not need or going without coverage that could save you thousands after an unexpected loss. This guide breaks down both coverages side by side so you can make a confident decision.
What Collision Insurance Covers
Collision insurance generally pays to repair or replace your vehicle after a covered crash, regardless of who caused it, subject to policy terms. If your car is totaled, payment generally reflects its actual cash value minus the applicable deductible, subject to policy terms.
Subject to policy terms, collision coverage can apply when your vehicle is damaged by:
- Crashing into another vehicle, whether you are at fault or not
- Single-vehicle accidents, such as running off the road or rolling over
- Hitting a stationary object like a guardrail, fence, post, or tree
- Pothole damage in some cases, depending on the insurer and the extent of damage
Collision does not cover mechanical breakdowns, routine wear, or damage from events like weather and theft. Comprehensive covers certain other causes of damage, but not mechanical breakdown or routine wear.
What Comprehensive Insurance Covers
Comprehensive insurance covers certain damage to your vehicle from events other than collisions, subject to policy terms and exclusions. It is sometimes called “other than collision” coverage on policy documents.
Subject to policy terms and exclusions, comprehensive coverage can apply when your vehicle is damaged by:
- Theft of the entire vehicle or parts (catalytic converters, wheels)
- Vandalism, including keying, broken windows, or graffiti
- Weather events such as hail, flooding, tornadoes, hurricanes, and fallen trees or branches
- Animal strikes, including hitting a deer or other wildlife
- Fire, whether from an engine fire, arson, or a nearby wildfire
- Falling objects like tree limbs, rocks, or debris
- Glass breakage, including cracked or shattered windshields
- Civil disturbance, including riots or protests that damage your vehicle
Comprehensive does not cover collision damage, mechanical failure, or personal belongings stolen from inside the car (your renters or homeowners policy may cover personal property).
Side-by-Side Comparison
| Feature | Collision | Comprehensive |
|---|---|---|
| What it pays for | Damage from crashes with vehicles or objects | Damage from non-crash events (theft, weather, animals, vandalism) |
| When it applies | A covered collision damages your car | A covered non-collision event damages your car |
| Deductible | Generally applies; check your policy | Generally applies; check your policy |
| Cost | Varies by quote and deductible | Varies by quote and deductible |
| Required for financed cars? | Lender may require it | Lender may require it |
| Fault requirement | Pays regardless of fault | Not fault-based (covers events outside your control) |
When You Need Both
Carrying both collision and comprehensive coverage makes sense when the cost of losing your vehicle would create a serious financial hardship. Common situations where you should have both include:
- You finance or lease your vehicle. Your lender or leasing company may require both coverages. If you owe more than your car is worth, consider whether gap insurance is available and appropriate; its terms and exclusions determine what it pays.
- You drive a newer car. Vehicles that are only a few years old still hold significant value, and the cost of replacing one out of pocket can be substantial.
- You cannot afford to replace your car with savings. If losing your vehicle would mean going without transportation or taking on debt, both coverages provide important financial protection.
- You drive for rideshare or delivery. Personal auto policies may exclude driving for pay, and coverage can vary by activity and app period. Review your policy, the platform’s coverage and any available rideshare or delivery endorsement with your insurer.
When You Might Drop One or Both
There are situations where carrying collision, comprehensive, or both may no longer be worth the cost:
- Your car’s market value is low. Compare the annual premium with your car’s current value, the deductible and your ability to replace it. For example, a $400 combined premium on a $3,000 car is one factor to weigh, not an automatic cutoff.
- You drive an older vehicle. As cars age, their value decreases, but premiums for physical damage coverage do not always drop at the same rate.
- You have enough savings to replace the car. If you could comfortably buy a replacement vehicle without insurance proceeds, you may choose to self-insure against these risks.
Keep in mind that even if you drop collision, you may still want to keep comprehensive. Compare its separate premium and deductible: events like theft and hail can happen to a car of any age. To learn more about how much auto insurance you actually need, review your full coverage options before making changes.
Cost Factors
Several factors influence what you will pay for collision and comprehensive coverage:
- Deductible choice. A higher deductible lowers your premium but increases your out-of-pocket cost when you file a claim. A lower deductible does the opposite.
- Vehicle age and value. A vehicle’s value and repair cost can affect its premium.
- Location. Where you live and park your car affects both coverages. Insurers may consider local risks when setting rates.
- Driving history. Insurers may consider your driving record when setting premiums.
- Claims history. Your claims history may affect rates, depending on the insurer and applicable state rules.
You can explore all the factors that affect your rate in our guide on auto insurance coverage types.
How Deductibles Work for Each
Collision and comprehensive generally have separate deductibles; available choices depend on the insurer and policy. Your deductible is the amount you pay out of pocket before your insurance covers the rest.
Here is how it works in practice:
- If you hit a guardrail and cause $4,000 in damage to your car, your collision deductible applies. With a $500 deductible, you pay $500 and your insurer pays $3,500.
- If a hailstorm damages your car and repairs cost $2,500, your comprehensive deductible applies. With a $250 deductible, you pay $250 and your insurer pays $2,250.
The coverage and deductible applied depend on the loss and policy terms. Ask your insurer how a claim involving more than one cause would be handled.
Glass deductible options and requirements vary by insurer, policy and state; check your policy before assuming a windshield claim has no deductible.
Frequently asked questions
Can I have comprehensive without collision?
Some insurers allow comprehensive without collision, but availability and combinations vary. Check with your insurer and lender before changing coverage.
Does comprehensive cover me hitting a deer?
Animal damage is generally a comprehensive loss, subject to the policy’s terms and deductible. Check the policy and ask your insurer how the circumstances of the loss are classified.
Should I drop collision on an old car?
It depends on your car’s current market value and your financial situation. Compare the premium, deductible and current vehicle value with your ability to pay for a replacement. Confirm any lender requirements before dropping coverage.
Is comprehensive or collision more expensive?
The relative price depends on your vehicle, location, insurer and deductible choices. Compare the separate premiums in your quotes.
Next Steps
- Review your current policy. Check whether you already carry both coverages by reading your declarations page.
- Evaluate your car’s value. Look up your vehicle’s current market value to determine whether collision and comprehensive are still cost-effective.
- Adjust your deductibles. Raising your deductible can lower your premium if you are comfortable with a higher out-of-pocket cost per claim.
- Compare quotes. Rates vary significantly between insurers. Get quotes from multiple companies to find the best price for the coverage you need. Our guide to comparing insurance quotes can help.
- Talk to your lender. If you are financing or leasing, confirm exactly what coverages your lender requires before making changes.