
2026-05-12 · auto, shopping
Updated: 2026-07-09
By InsuraFAQ Editorial Team · Reviewed for accuracy
Best Auto Insurance Companies
At a glance
- How to choose: Compare on coverage fit, service, and price — not price alone.
- Financial strength: Review independent financial-strength ratings alongside other factors; a rating is not a guarantee that claims will be paid.
- Service signal: Use the NAIC complaint index and J.D. Power Auto Insurance Study to gauge claims experience.
- Coverage flexibility: Adjust limits, deductibles, and add-ons to your driver profile.
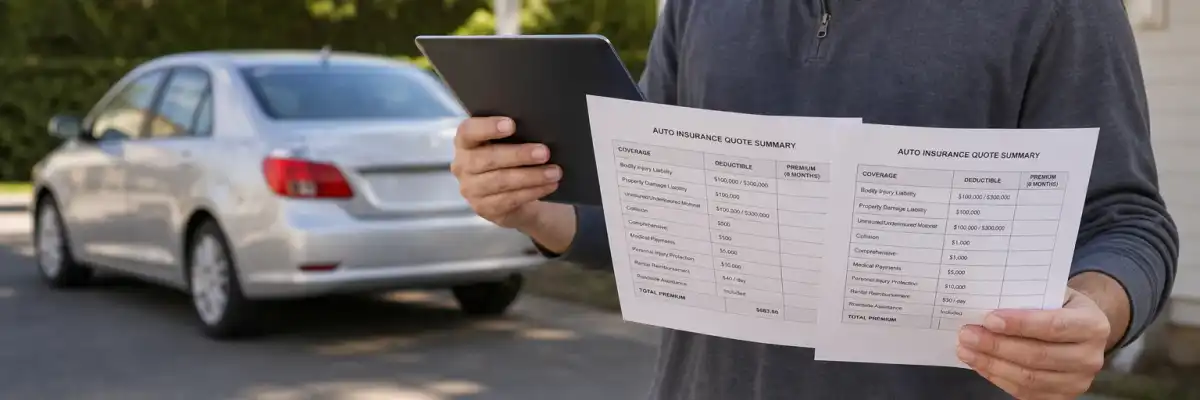
- Shopper move: Run three quotes with identical limits, deductibles, and endorsements; ask about the policy term, discounts, and how renewal prices may change.
Overview
The best auto insurer is the one that fits your driver profile, coverage needs, and claims expectations. Use a consistent checklist instead of chasing the lowest price alone.
What to compare
- Coverage flexibility: ability to adjust limits, deductibles, and add-ons.
- Discounts: safe driver, bundling, low mileage, and telematics options.
- Claims experience: customer satisfaction and claims response time.
- Financial strength: ability to pay claims after large events.
Fit by driver profile
- New drivers: prioritize education discounts and flexible deductibles.
- High-risk drivers: look for SR-22 support and forgiveness programs.
- Low-mileage drivers: usage-based or pay-per-mile options can help.
- Military families: confirm deployment and storage discounts.
- Rideshare and delivery drivers: confirm the carrier offers a rideshare or delivery endorsement, because personal auto policies may exclude driving for pay; review the policy and the rideshare coverage guide.
- Drivers with significant assets to protect: confirm the carrier writes an umbrella policy and ask about required underlying auto liability limits and exclusions.
Next steps
Create three comparable quotes with the same limits, then choose the carrier that balances price with coverage quality.
How to build a fair carrier comparison
- Lock the same coverage limits, deductibles, and endorsements across every quote. Quotes are only comparable when the inputs match. See how to compare insurance quotes for a step-by-step walkthrough.
- Request quotes with identical driver, vehicle, and garaging information so rating variables do not skew results.
- Check the policy term and ask which discounts apply now and whether they can change at renewal.
- Score three dimensions, not just price: premium, claims reputation (J.D. Power or the NAIC complaint index), and independent financial-strength ratings.
What to have ready before you request quotes
- Current declarations page showing liability, collision, comprehensive, UM/UIM, medical payments/PIP, and any endorsements.
- Driver information: license number, date of birth, years licensed, and accidents or violations in the last 3 to 5 years.
- Vehicle details: VIN, annual mileage, primary use, garaging address, and whether it is financed or leased.
- Any prior coverage lapse, SR-22 requirement, or at-fault claim history.
- Existing discounts you want to verify: multi-policy, good student, defensive driving, telematics, paid-in-full, paperless.
Common mistakes when comparing carriers
- Comparing minimum-limit quotes to higher-limit quotes and assuming the cheaper one is the better deal.
- Ignoring uninsured/underinsured motorist coverage limits, which are often the difference between a real recovery and an unpaid medical bill when an uninsured driver hits you.
- Dropping collision or comprehensive without checking whether a lender still requires it.
- Skipping the NAIC complaint index and J.D. Power claims satisfaction scores, which are free and signal claims experience better than marketing.
- Assuming the quoted premium or discounts will remain unchanged at renewal.
When to re-shop your auto policy
- At every renewal, run three fresh quotes with identical limits to your current policy.
- After any life change that moves you into a new rating tier: marriage, a new address, a new vehicle, adding a teen driver, or paying off a loan.
- After a surcharge changes or expires; timing and rating rules vary by insurer and state.
- If your telematics program is ending or your discount tier is changing.
- Any time your current carrier raises the rate by more than general inflation at renewal. When you do switch, follow the guidance on switching carriers without a gap so you stay continuously covered.